Saver's Match 2027: The $1,000 Math
If an IRS letter with the code CP321J landed in your mailbox this fall, it was not a bill. It was an early warning about the best retirement deal most low and moderate income savers have ever been offered. Starting with contributions made in 2027, the Saver's Match, created by the SECURE 2.0 Act, replaces the Saver's Credit for retirement accounts. The government will deposit 50 percent of the first $2,000 you contribute, up to $1,000 per person, directly into your retirement account, according to the IRS Saver's Match page. Reporting on the IRS notices, including this Investopedia account of the CP321J mailings, confirms that no action is needed in 2026. The action is planning, and it starts with knowing whether you are inside the income lines.
The income lines for 2027
| Filing status | Full 50% match up to | Match reaches zero at |
|---|---|---|
| Single | $20,500 | $35,500 |
| Head of household | $30,750 | $53,250 |
| Married filing jointly | $41,000 | $71,000 |
Between the two numbers in each row the match phases out gradually rather than falling off a cliff. Each spouse in a joint return gets a separate match on their own contributions, so a qualifying couple who each save $2,000 can receive $2,000 in total. You must be 18 or older, not a dependent, and not a full-time student. Crucially, you can qualify even if you owe little or no tax, which is the flaw in the old credit this program fixes: the old Saver's Credit was nonrefundable, so the people with the smallest tax bills got the smallest benefit, or none. Our 401(k) catch-up math covers the workplace-plan side of saving; this match stacks on top of contributing, it does not replace the habit.
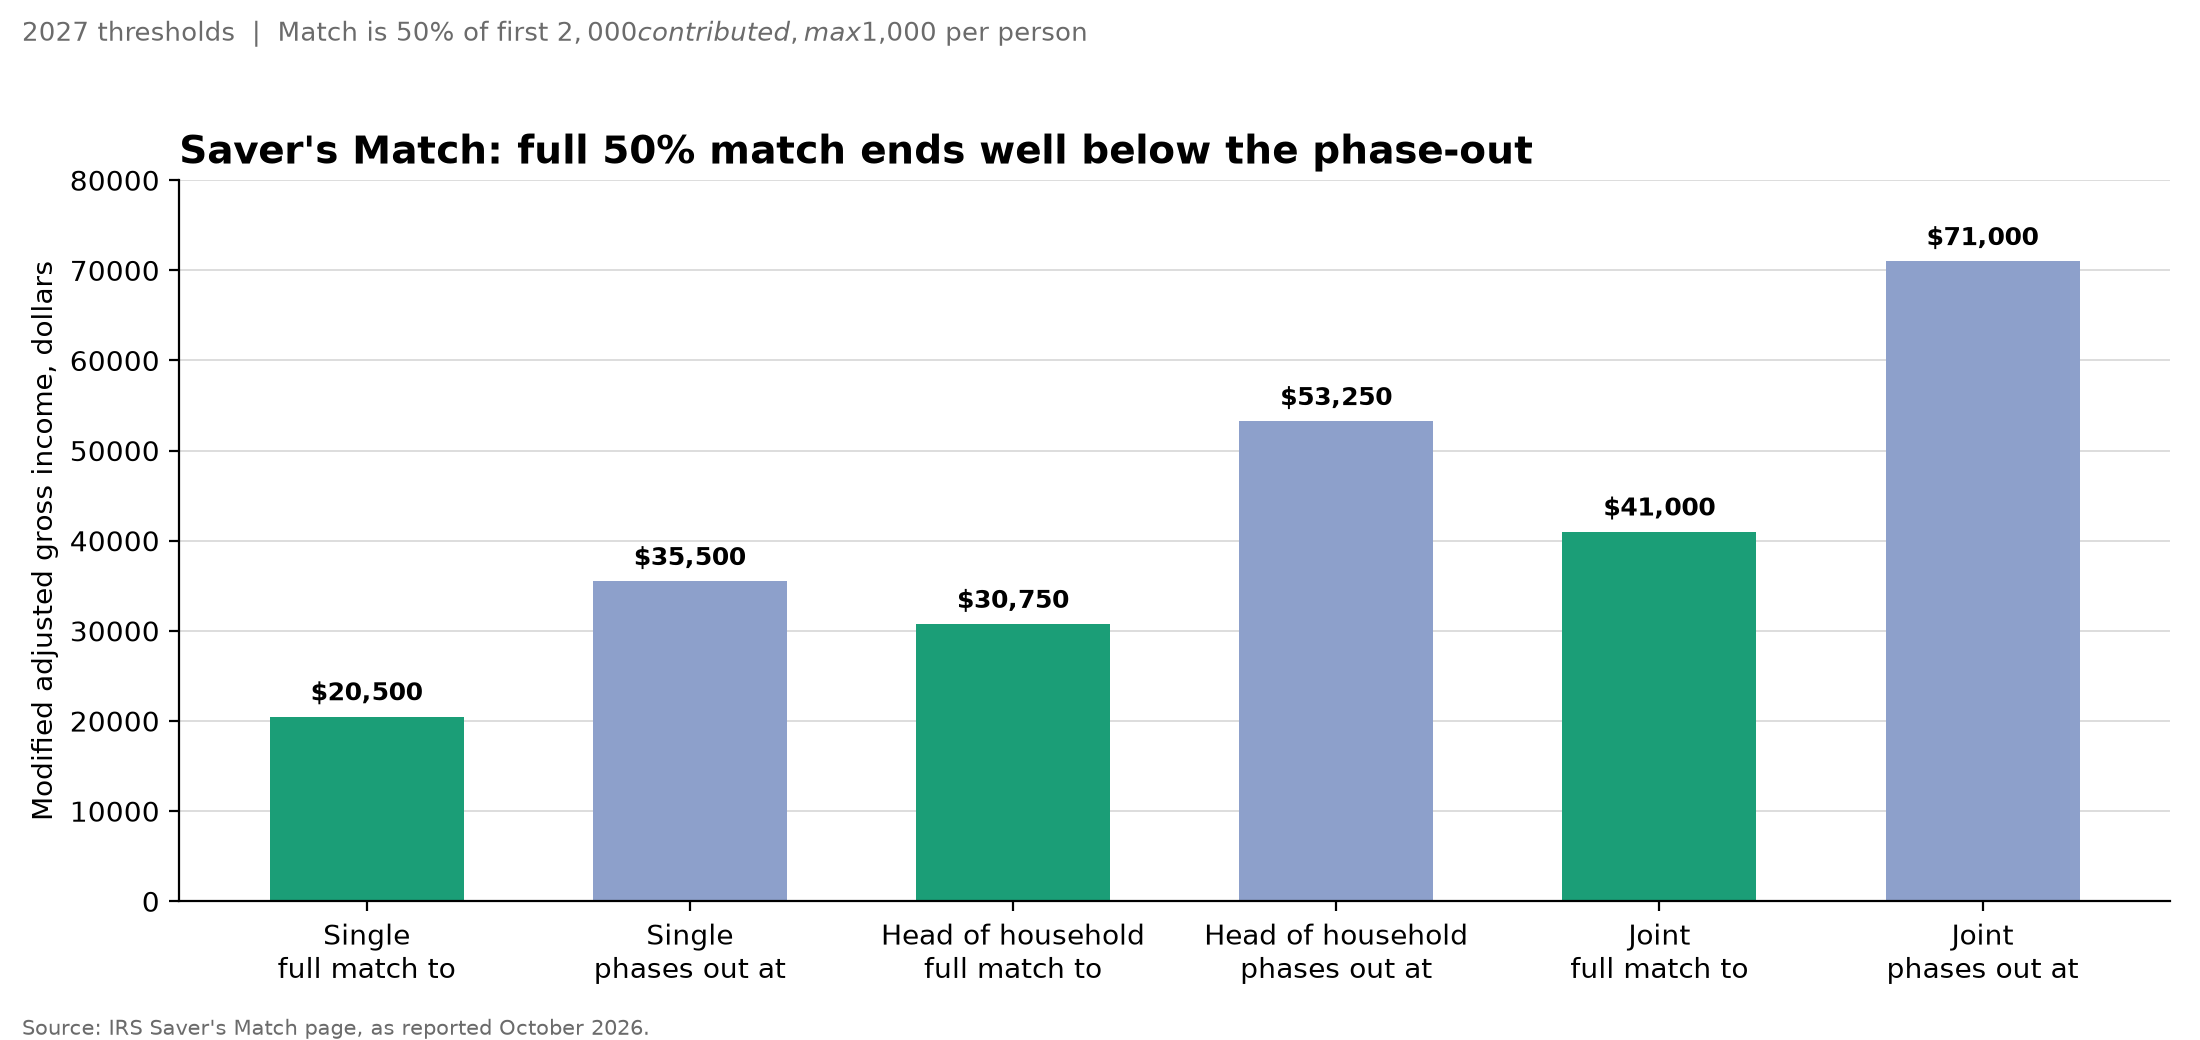
Figure 1: 2027 Saver's Match income thresholds by filing status. Source: IRS.
Three worked examples
Example 1, full match. A single filer earning $19,000 contributes $2,000 to an IRA during 2027. Match: 50 percent of $2,000, which is $1,000, deposited into the account after the 2027 return is filed in 2028 on Form 8880-A. Total saved in one year: $3,000, of which the saver funded two thirds.
Example 2, small contributions still count. There is no minimum contribution. The same saver contributing only $600 receives $300 at the full rate. That is the point I make in our pay yourself first math: at this income, a 50 percent instant return beats any market return you will ever be promised.
Example 3, a couple in the phase-out. A joint couple earning $55,000, between the $41,000 full-match line and the $71,000 zero line, receives a reduced match rather than nothing. The exact percentage comes from the Form 8880-A calculation for their income, so I am not inventing a figure here; the planning point is that each spouse should contribute in their own name, because the match is per person, not per return.
What to do in the next 60 days
Do nothing with the notice itself. Do three practical things instead. First, confirm you have an eligible account, a 401(k), 403(b), governmental 457(b), or a traditional or Roth IRA, and open an IRA in 2027 if you have none. Second, set a 2027 contribution you can actually sustain, even $50 a month, which is $600 a year and $300 of match at the full rate. Third, put a note in your 2028 filing folder now: Form 8880-A is how the match is claimed, and unclaimed matches are how well designed programs quietly fail. One more detail worth knowing before you plan around the money: the match is deposited into the account you designate on the claim, and once it lands it is retirement money under the usual rules, not a refund you can redirect to rent. Treat it in your budget as invisible. The households who benefit most from programs like this are the ones who never adjust their spending upward because the match exists, so the full $1,000 compounds for decades instead of dissolving in the year it arrives.
Pair this with the year-end moves in our 2027 tax brackets comparison and you have the full low-income saver picture for next year.
Get the newsletter
New articles and the occasional deep dive. No spam.
Unsubscribe anytime. We never sell your email.