I Bonds Reset Nov 1: Wait, or Buy by Oct 29?
Every I Bond buyer faces the same fork this week, and it closes fast. Bonds bought through the end of October pay a confirmed composite rate of 4.26 percent, built from a 0.90 percent fixed rate plus a 3.34 percent annualized inflation rate, as laid out in the TIPSWatch I Bond Q and A. The November 1 reset is not official yet, but every published estimate points the same way: up. Money Talks News, reporting TIPSWatch founder David Enna's forecast, puts the likely fixed rate at 1.3 percent, possibly 1.4 percent, and one worked estimate lands at a 4.90 percent composite. A second estimate, using a 4.08 percent inflation component, lands near 5.41 percent. I ran both below, because a decision checklist built on one forecast is a guess wearing a tie. This is the follow-up decision to our earlier buy-before-October-31 guide, written when the case for buying early was stronger than it is now.
The two doors, priced on 10,000 dollars
| Buy by Oct 29 | Wait for Nov 1 | |
|---|---|---|
| Composite rate, first 6 months | 4.26% (confirmed) | About 4.90% to 5.41% (estimates) |
| Fixed rate, locked for 30 years | 0.90% | About 1.30% (forecast) |
| Interest on 10,000 dollars, first 6 months | About 213 dollars | About 245 to 270 dollars |
| Inflation rate after your first reset | New rate applies at your 6-month mark | Same new inflation rate |
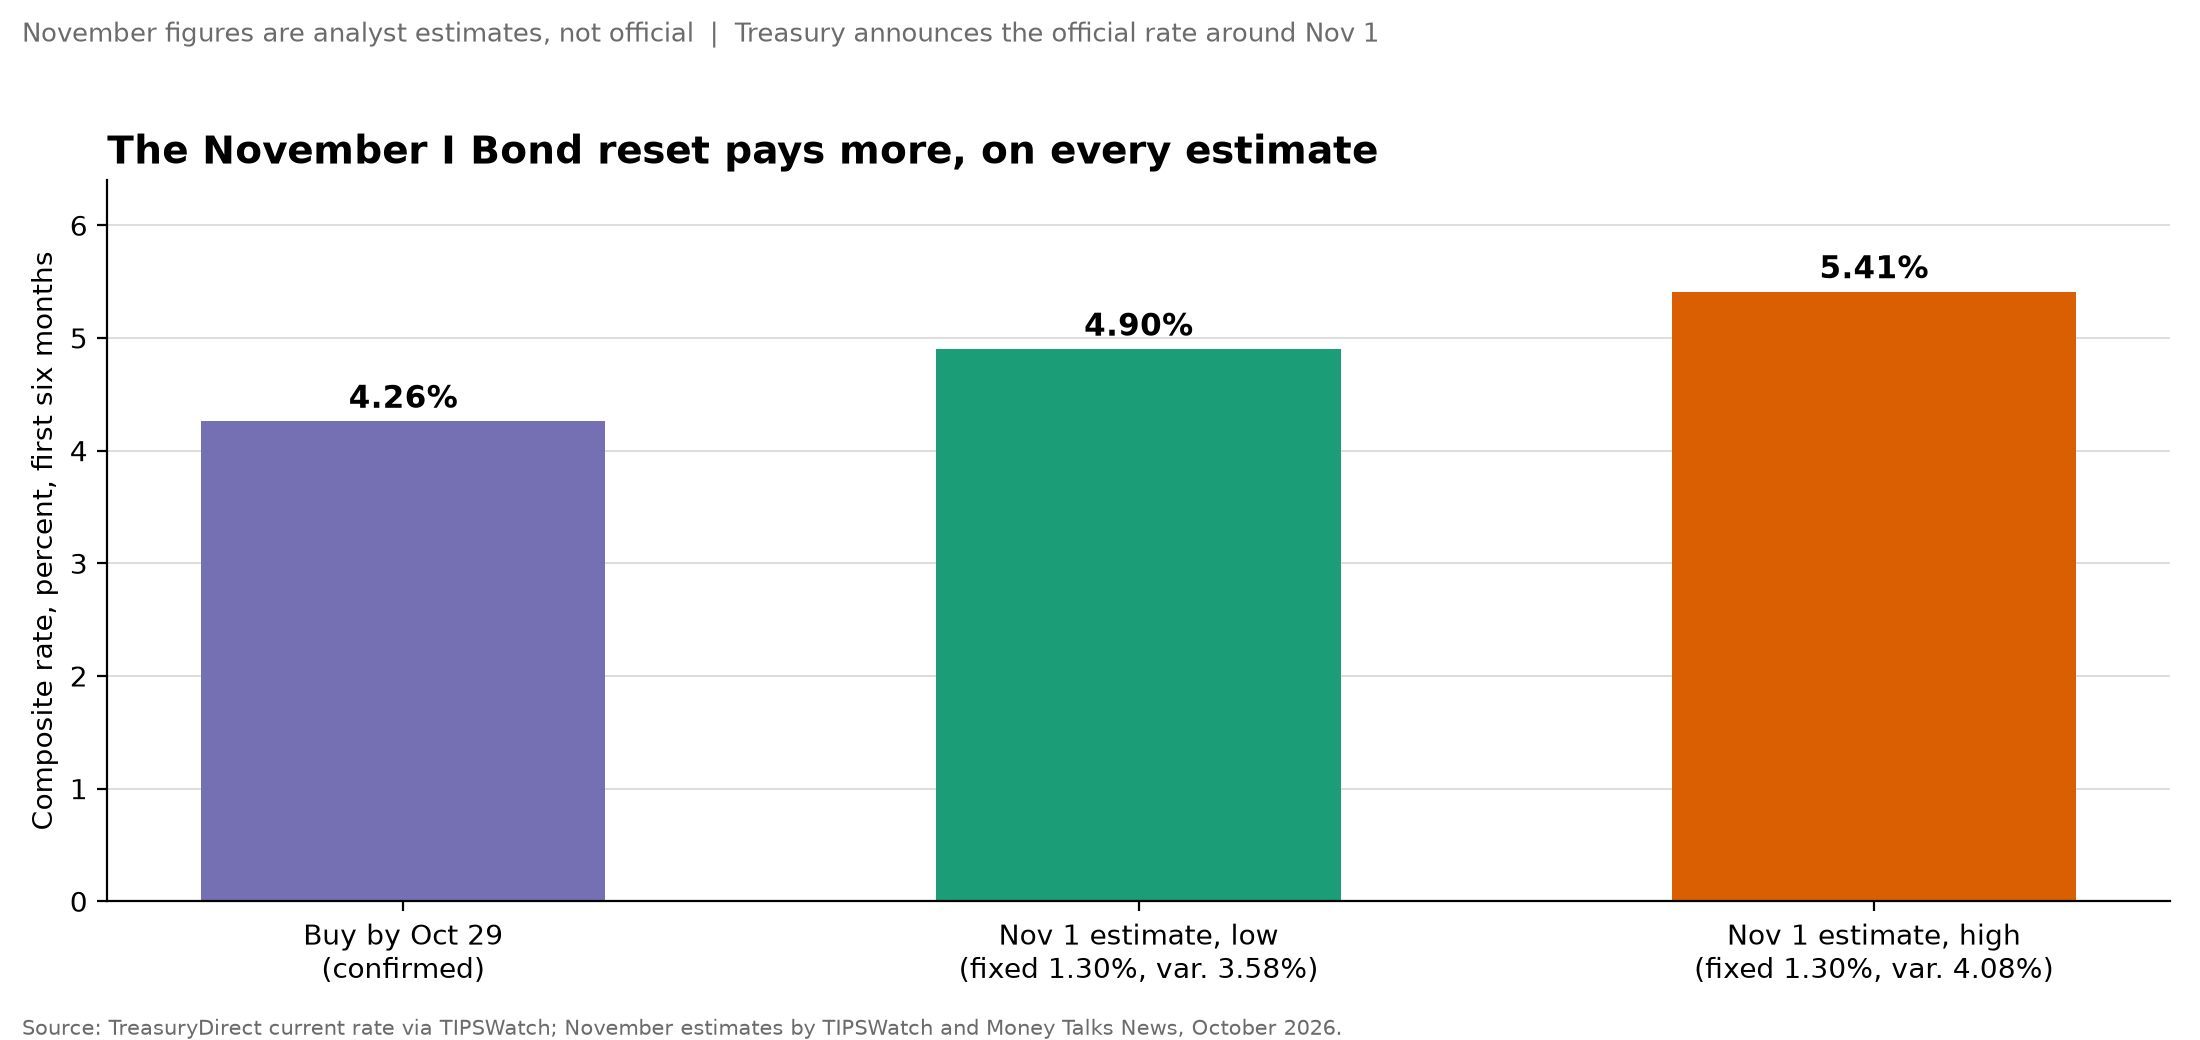
Figure 1: Confirmed October composite versus November estimates. November figures are analyst estimates, not official. Source: TreasuryDirect via TIPSWatch; estimates by TIPSWatch and Money Talks News, October 2026.
Read the table the way I do. The six-month interest gap, roughly 32 to 57 dollars on a full 10,000 dollar purchase, is small. The fixed-rate gap is the durable part: 0.90 versus about 1.30 percent is 0.40 points, worth about 40 dollars a year on 10,000 dollars, every year, for as long as you hold the bond. The inflation component is not a reason to time anything, because it resets onto every bond, old and new, at each bond's own six-month mark.
The deadline nobody is advertising
Two dates matter more than the rate. First, a local money briefing summarizing TreasuryDirect's notices reports that a purchase must be finished by 11:59 p.m. on Thursday, October 29 to lock the current 4.26 percent rate, and that ID.me login becomes required at TreasuryDirect starting October 29. Second, the annual limit is 10,000 dollars per person per calendar year, so waiting for November costs you nothing in capacity if you have not bought yet, but a household that buys 10,000 dollars each in late October cannot add November bonds until January. If you hold older low-fixed-rate bonds and are weighing a swap, The Finance Buff's sell-and-rebuy analysis makes the case for selling when the new fixed rate rises, and its warning about TreasuryDirect service delays is worth reading before you start.
My checklist before you click buy
- Buying for the first time this year, and the money can sit 12 months? Wait for November 1 and take the higher fixed rate.
- Already bought your 10,000 dollars for 2026? There is no decision. The new inflation rate reaches your bonds at their reset dates on its own.
- Need the purchase dated in October for your own records? Finish by October 29, not October 31, and set up ID.me first so the login change does not lock you out mid-purchase.
- Cashing out early either way? Remember the rules that do not change: no redemption in the first 12 months, and a 3-month interest penalty before 5 years, the same rules behind our high-yield savings fine print guide.
- Splitting a household purchase? Each person's 10,000 dollar limit is separate, the same per-person logic as the Saver's Match worked example.
My own call, for my own money: I am waiting. A forecast is not a rate, and I have labeled every November number here as an estimate because the Treasury has not announced it. But the fixed rate is the one component that never resets, two independent estimates agree it rises, and the cost of waiting four days is a few dollars of six-month interest. That trade is easy.
Get the newsletter
New articles and the occasional deep dive. No spam.
Unsubscribe anytime. We never sell your email.